Armenia is experiencing a steady increase in financial fraud, particularly in the banking sector. The most common schemes are not technical hacks, but social engineering operations — designed to exploit human behavior rather than system vulnerabilities.
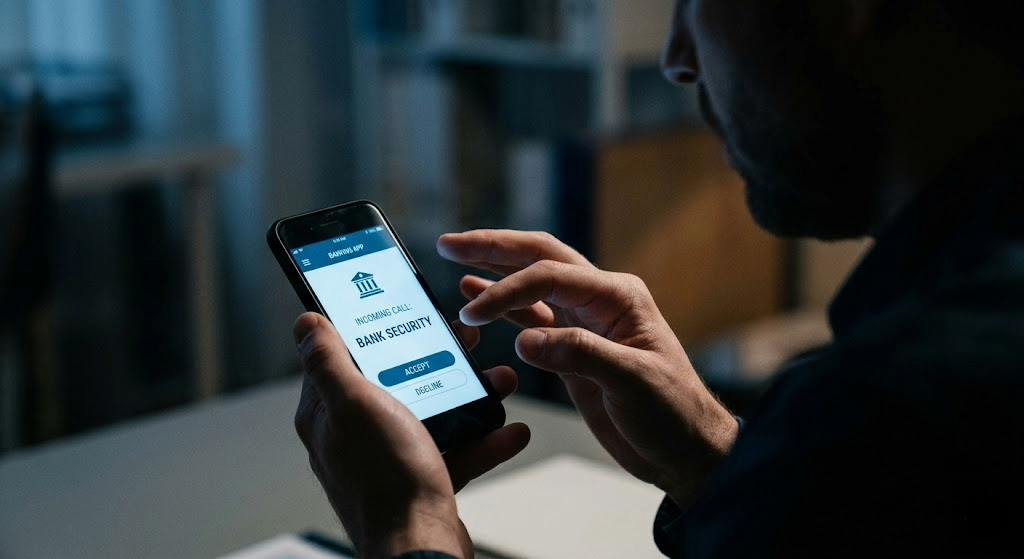
Recent warnings from financial institutions highlight a surge in so-called “bank impersonation” scams. Individuals receive calls from fraudsters posing as bank representatives, often claiming urgent security issues.
The objective is simple: extract sensitive information.
How the Schemes Work
The structure of these scams is consistent:
- The caller claims to be from a bank’s security department
- The victim is told their account is at risk
- Urgency is introduced to prevent verification
- The victim is asked to provide:
- Login credentials
- Card details
- One-time passcodes (OTP)
Once an OTP is disclosed, funds can be transferred immediately. From a system perspective, the transaction appears legitimate.
Why This Matters
At first glance, these incidents appear to be isolated cases of fraud. In reality, they reveal broader systemic vulnerabilities.
1. Human Factor as the Weakest Link
Financial systems have become more secure at the technical level. As a result, attackers have shifted toward manipulating users directly.
This aligns with global trends:
- The majority of cyber-enabled fraud now involves social engineering
- Human behavior has become the primary attack surface
2. Limited Consumer Protection Post-Transaction
Once a transaction is authenticated using valid credentials and OTP, banks often classify it as authorized.
This creates a structural gap:
- The system protects access
- It does not protect decision-making under deception
3. Trust as a Vulnerability
These scams rely heavily on institutional trust.
The more credible the banking system appears, the easier it becomes for attackers to imitate it.
The Link to Governance
Financial fraud does not exist in isolation from broader governance issues.
Environments with:
- Limited enforcement visibility
- Weak consumer protection mechanisms
- Inconsistent accountability
tend to provide more opportunities for organized fraud networks.
While Armenia has made progress in regulatory reform, enforcement consistency remains uneven — particularly in areas involving financial crime.
The Scale of the Problem
Available data indicates:
- Hundreds of fraud cases reported within short timeframes
- Increasing reliance on digital banking channels
- Low recovery rates once funds are transferred
At the same time, corruption-related offenses — including fraud, embezzlement, and abuse of power — continue to be recorded annually in significant numbers.
The overlap is not coincidental.
What Needs to Change
Reducing fraud requires more than public warnings.
Key areas include:
- Stronger transaction monitoring tied to behavioral anomalies
- Clearer liability frameworks for fraud losses
- Faster response mechanisms for freezing suspicious transfers
- Public education focused on real attack scenarios
Most importantly, enforcement outcomes must be visible and consistent.
Conclusion
The rise in digital fraud in Armenia is not just a cybersecurity issue. It is a signal.
It reflects:
- A shift in how financial crime is executed
- Gaps in user-level protection
- Broader structural weaknesses in enforcement and accountability
As financial systems become more advanced, the threat landscape is becoming more human.
And that is where the system is currently least prepared.